What Should You Do With Your Life Insurance Policy?
Confused about what should you do with your life insurance policy?

Image description
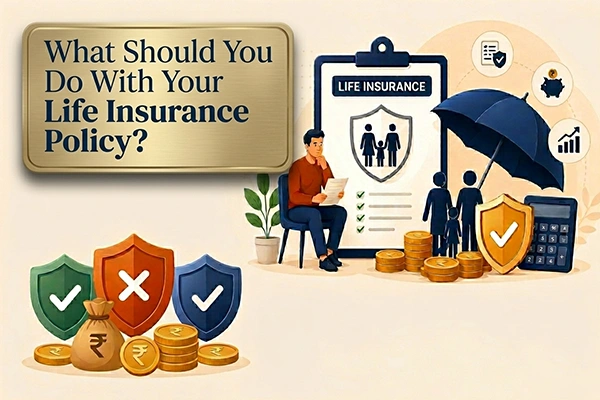
Infographic headed 'Confused about what should you do with your Life Insurance Policy?'. Four icons below the heading are labelled: Financial Protection; Smart Decisions; Know Your Options; Better Returns. The illustration shows a man seated reading a document beside a large clipboard titled 'Life Insurance', which shows a family inside a shield and a checklist, along with an umbrella over a family, stacks of rupee coins, a shield with a check mark, a calculator, and small icons of a document, a piggy bank and a rising chart. A bottom panel titled 'What Should You Do?' lists three options: 1. Continue the Policy (green shield with check mark); 2. Surrender the Policy (money bag with a cross); 3. Convert to Paid-Up Policy (blue shield with check mark).
In Indian families, pressure to buy traditional life insurance policies can be strong and multifaceted. Parents often play the “security card,” emphasizing the importance of safeguarding their child’s future and highlighting potential future burdens or painting a picture of an uncertain future without the policy. The pressure is higher if the agent is a relative or a family friend.
Unfortunately, some insurance agents and bankers may mislead people into buying life insurance policies that are not a good fit for their needs. The insurance agents/ bankers might pressure to buy a policy on the spot, instead of giving you time to consider their options. Or, they might make promises about the policy that seem too good to be true, such as guaranteed high returns. In some cases, people may not even fully understand the terms, coverage, or exclusions of the policy before they buy it.
Have you been Dumped into any traditional life insurance policy like this which is neither giving you adequate insurance coverage nor investment return? It happens! traditional life insurance policies can be complex and sometimes you are pushed products that aren’t the best fit. That’s really a frustrating situation. Traditional life insurance can sometimes be oversold or missold, especially if it doesn’t match your needs. Don’t worry we are here to solve your biggest question What should you do with your life insurance policy ?
3 Steps to Assess Your Traditional Life Insurance Policy
Before deciding what should you do with your life insurance policy consider assessing the below 4 steps:
- Understand your policy: Get a copy of your policy document and read it thoroughly. It will outline the type of policy (money back, endowment, ULIP etc.), sum assured, premium amount, and terms and conditions.
- Review your needs and goals: Reflect on what you were hoping to achieve with this policy. Was it life cover, saving for a child’s education, or retirement planning?
- Explore options: Don’t feel pressured to stick with a policy that doesn’t serve you. Take time to understand your options and choose what works best for your financial situation and goals. Talk to your financial advisor/ LIC agent about the various options that you have.
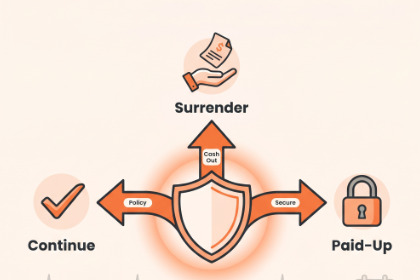
What should you do with your life insurance policy ? 3 Options to consider.
- Continuing the policy
- Surrender the policy
- Convert to Paid-Up policy
Let us go through all the 3 options and decide what should you do with your life insurance policy:
Continuing the policy:
It refers to a policy that is still active and in force. This means you’ve been paying the premiums on time and haven’t opted to take any actions that might terminate the policy. Let us look into the various pros and cons of continuing your traditional life insurance policy.
Pros:
- Guaranteed Death Benefit: Your beneficiaries receive a pre-determined sum assured (death benefit) regardless of when you pass away. This offers financial security for them.
- Predictable Premiums: Unlike term life insurance, premiums for traditional policies typically remain fixed throughout the policy term. This allows for easier budgeting.
- Cash Value Accumulation (Some Policies): Many traditional policies (whole life, endowment) build cash value over time. You can access this value through loans or withdrawals (subject to fees and policy terms).
- Tax Benefits (Potential): Premiums paid towards traditional life insurance policies might be eligible for tax deductions under section 80C of the Income Tax Act.
Cons:
- Lower Returns: Traditional policies often have lower returns on your investment compared to other options like stocks or mutual funds.
- Fees and Charges: There can be surrender charges (fees for cancelling early), administrative fees, and mortality charges that eat into your returns.
- Limited Flexibility: Traditional policies are typically less flexible than other investment options. Changing coverage or investment options within the policy might be difficult.
- Opportunity Cost: By putting money into a traditional policy, you might miss out on potentially higher returns elsewhere.
If you continue the Policy:
- Death Benefit: Your beneficiaries receive death benefits if the insured person passes away during the policy term.
- Maturity Benefit: If the insured person outlives the policy term Upon maturity, he will receive the sum assured along with accumulated bonus if any.
Drawback:
The 4% return might be lower than what you could potentially earn in other investment options. There might be additional fees impacting the overall return.
When can you continue with the policy?
- Policy is near maturity: If you have already paid 80% to 90% of the premiums and the policy is close to maturity then you can continue paying premiums.
- You value guaranteed benefits: If it somewhat aligns with your needs where the guaranteed death benefit and predictable premiums are important to you, and you don’t necessarily need high returns, then continuing might be okay.
- Limited investment knowledge: If you’re not comfortable with managing investments yourself, a traditional policy can offer a simpler way to save and get some guaranteed benefits.
But factor in the opportunity cost of potentially lower returns compared to other investments and understand the impact of fees on your overall return. There’s no one-size-fits-all answer. Consider your financial goals, risk tolerance, and the specific features of your policy before deciding to continue explore other available alternatives.
Surrender the policy:
Surrendering a traditional life insurance policy means terminating it before maturity and receiving a surrender value from the insurance company. This can be a tempting option if you’re unhappy with the policy, but it’s crucial to understand the implications before making a decision.
Pros:
- Access Cash: You receive immediate access to the surrender value, which can be helpful for emergencies or other financial needs.
- Reduce Financial Burden: If you’re struggling to keep up with premiums, surrendering can free up some cash flow.
- Invest Elsewhere: You can use the surrender value to invest in a product that potentially offers higher returns, like mutual funds or stocks (be aware of associated risks).
Cons :
- Loss of Coverage: Your beneficiaries lose the guaranteed death benefit upon surrender. This can leave them financially vulnerable in case of your demise.
- Lower Surrender Value: The surrender value is typically less than the total premiums you’ve paid, especially in the early years of the policy. You might incur significant losses.
- Tax Implications: In India, the surrender value from traditional policies might be taxable depending on the policy type and number of years it has been active. Consult a tax advisor for specific details.
Surrendering a traditional life insurance policy can be a significant financial decision. Carefully weigh the pros and cons, understand the surrender value you’ll receive, and consider potential tax implications before proceeding with this option.
Paid up policy:
If you’re unhappy with the premiums of your traditional life insurance policy but don’t want to surrender it completely, converting it to a paid-up policy can be an option. You can convert your policy to a paid-up policy and divert the further premiums & maturity proceeds to a better investment option. A paid-up policy ensures that the policy is in force, and you get pro-rata benefits. The amount invested along with the growth will be accessible along with maturity.
Here’s a breakdown of the pros and cons ;
Pros :
- Reduced Premiums: You stop paying future premiums, offering immediate financial relief.
- Reduced Death Benefit (Guaranteed Coverage): The death benefit is reduced proportionally to the number of premiums paid. However, it provides some guaranteed payout to your beneficiaries.
- Policy Remains Active: The policy continues until maturity or death, offering some life cover even without further premiums.
Cons :
- Lower Death Benefit: Your beneficiaries receive a lesser payout compared to the original death benefit.
- Reduced Cash Value Growth: Since no further premiums are paid, the cash value (if any) grows minimally based on declared bonuses by the insurer.
- Potential Loss of Riders: Additional benefits attached to the policy (riders) like accidental death benefit might be discontinued upon conversion.
Converting your traditional life insurance policy to a paid-up option can be a way to manage premium payments but comes with a reduced death benefit. Carefully analyze your needs, understand the impact on the death benefit and cash value, and explore alternatives before making a decision.
The deciding moment: What should you do with your life insurance policy – Continue vs Surrender vs paid-up policy?
Let us understand the above 3 options with an example;
Let’s say you have a 20-year endowment policy with 3 scenarios as mentioned below;
| Particulars | Scenario 1 | Scenario 2 | Scenario 3 |
|---|---|---|---|
| Policy Tenure | 20 years | 20 years | 20 years |
| Annual premiums | 42,000 | 42,000 | 42,000 |
| Sum Insured | 10,00,000 | 10,00,000 | 10,00,000 |
| After 5 years of policy premium payments | Continued | Surrendered | paid-up |
| How to calculate surrender value / Reduced paid up value? | NA | 30% of the total premiums paid till the surrender of the policy | Reduce Paid-up value = (Sum Assured) * (Number of Premiums Paid) / (Total Number of Premiums) |
| Surrendered value/ reduced paid up value | NA | ₹ 63,000.00 | ₹ 2,50,000.00 |
| Payment will be made on | On maturity | Immediately after the surrender of the policy | On maturity |
| Scope of Reinvesting Further premiums | No | Yes | Yes |
| Reinvestment in equity @10% p.a | NA | Surrender value + Future premiums for the next 15 years | Future premiums for the next 15 years |
| Future value (approximately) | ₹ 14,00,000 | ₹ 17,31,000 | ₹ 17,17,900 |
Scenario 1: calculations for continuing the policy
₹ 10,00,000 Sum assured along with accumulated bonus of ₹ 4 lakhs will be paid on maturity date
Scenario 2: calculations for Surrendering the policy and reinvesting it in Equity investments
Assuming the surrendering value is 30% of the total premiums paid for the 5 years i.e., ₹ 63,000 (42000*5*30%)
Let us say that you have reinvested the surrendered value along with the future annual premiums in an equity mutual fund with a historical average return of 10% per year.
The future value you will be receiving in 2039 will be around ₹ 17.31 Lakhs.
Apply Future value formula in the excel: FV(rate,nper,pmt,pv,type)
=FV(10%,15,-42000,-63000,1)
=₹ 17,31,055
Rate = 10%
Nper = 15 years left after surrendering the policy
Pmt will be annual premiums = -42,000
Pv is the surrender value = -63,000
Scenario 3: calculations for Converting to a reduced paid-up policy
Reduced Paid-up value = (Sum Assured) * (Number of Premiums Paid) / (Total Number of Premiums)
Paid up value = 10,00,000*(5/20) = ₹ 2,50,000 which will be paid to on maturity date
Further Annual premiums will be invested in an equity mutual fund with a historical average return of 10% per year.
The future value you will be receiving from equity investments in 2039 will be around ₹ 14.67 Lakhs.
Apply Future value formula in the excel: FV(rate,nper,pmt,pv,type)
=FV(10%,15,-42000,0,1)
=₹ 14,67,888
Total Future value in case of scenario 3 is = ₹ 17,17, 889 (i.e., ₹ 14,67,888+2,50,000)
Rate = 10%
Nper = 15 years left after surrendering the policy
Pmt will be annual premiums = -42,000
Pv is the surrender value = 0
Disclaimer: While continuing the policy, you will get guaranteed returns but surrendering or converting it to a paid-up option and reinvesting the premiums in equity markets will not assure you guaranteed returns and is subject to market risk. Do consider risk appetite and your investment horizon when you’re investing in Equity.
The Emotional Tug-of-War while deciding what should you do with your life insurance policy? : Beyond the numbers and financial implications, surrendering your traditional life insurance policy or converting it to a reduced paid-up option can evoke a range of emotions. The low surrender value can feel frustrating and angry on insurance companies, especially if you’ve been paying premiums diligently for years.
The decision regarding what should you do with your life insurance policy – continue paying premiums, surrender it, or convert to a reduced paid-up option – is a significant one. Remember Surrendering is a permanent decision with lasting consequences i.e., losing the coverage. Converting to a reduced paid-up option reduces your death benefit but offers a way to keep some coverage without future premiums.
Each path offers unique advantages and drawbacks, and the optimal choice hinges on your specific circumstances. There’s no one-size-fits-all answer. Consider your financial goals, risk tolerance, and the specific features of your policy before deciding what should you do with your life insurance policy. Schedule a free introductory call today to understand the benefits of working with a financial planner.