The Magic of Dynamic Asset Allocation
Why Choose Dynamic Asset Allocation Over Static Allocation?
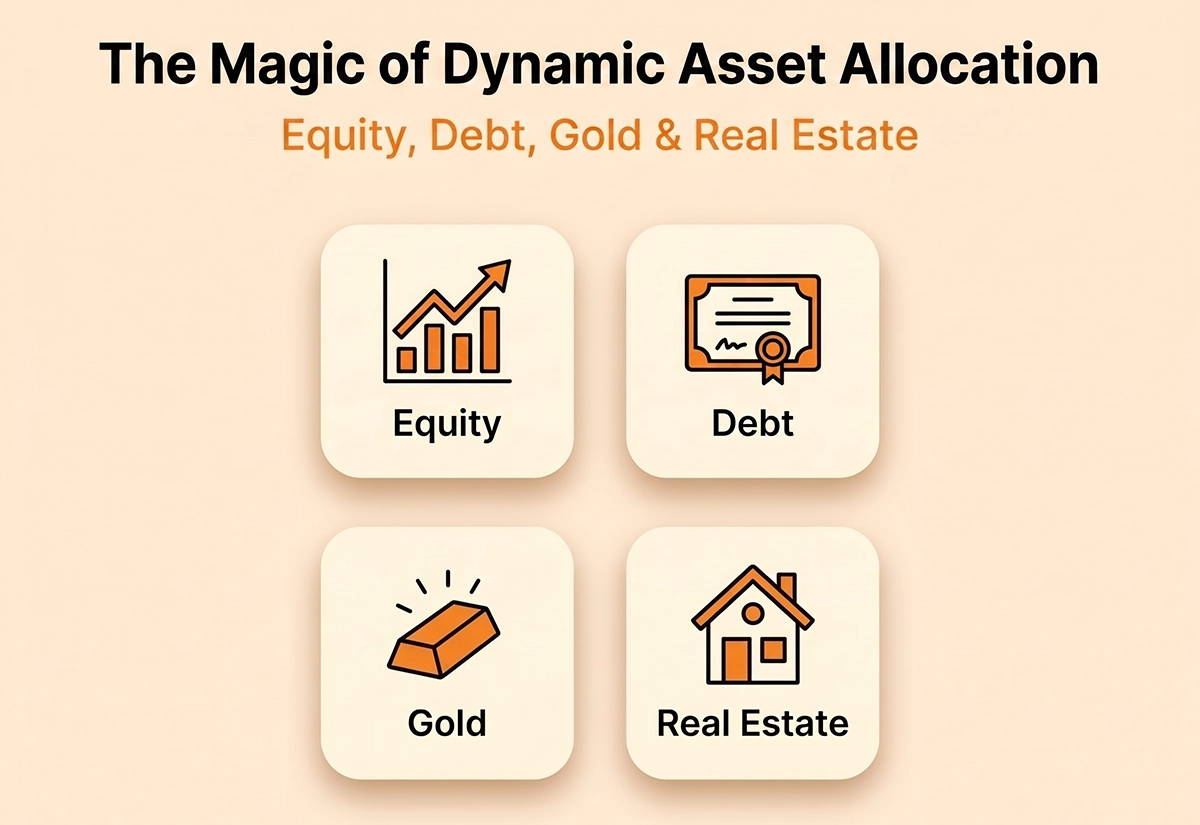
Image description
Title: The Magic of Dynamic Asset Allocation. Subtitle: Equity, Debt, Gold & Real Estate. Four tiles in a two-by-two grid, one for each asset class: Equity (rising bar chart with an upward arrow) | Debt (certificate with a seal) | Gold (gold bar) | Real Estate (house). The image introduces the four asset classes covered by a dynamic asset allocation strategy.
What Is Asset Allocation?
You must have observed that street vendors often sell unrelated products – such as raincoats and sunglasses? Initially, it seems odd. After all, when can a person buy both items at the same time? Probably never – and that’s the point. Street vendors know that when it’s raining, it’s easier to sell raincoats but harder to sell sunglasses. And when it’s sunny, the reverse is true.
Asset allocation is a strategy of diversifying the investments in different asset classes like equity, debt, gold, real estate. Dynamic asset allocation is an investment strategy wherein the investor buys and sells the different investments in order to keep the allocations based on predefined parameters.
Why Dynamic Asset Allocation?
Why would a street vendor often sell unrelated products? By selling both items – in other words, by diversifying the product line – The vendor is reducing the risk of losing business on any given day. Dynamic Asset allocation is similar to the above example by investing in equity, debt, fixed deposit, gold, real estate, etc., investment risk gets minimized and superior return are generated for each unit of risk taken.
Dynamic Asset Allocation Based on Market P/E Ratios
Let us know look at Dynamic Asset Allocation between debt and equity instruments based on P/E ratios (price to earnings). The price-to-earnings ratio (P/E ratio) is the ratio for valuing a company that measures its current share price relative to its per-share earnings (EPS). The price-to-earnings ratio is also sometimes known as the price multiple or the earnings multiple.
Since the long term average P/E ratio of the Sensex is around 18, we have considered the start points around dates where the P/E ratio was close to 18. An initial investment of ₹ 1,00,000/- is completely invested in equity and 40% of the corpus is shifted to debt instruments when the market P/E reaches 24 times to protect the portfolio. Higher market PE ratios indicate overvaluation and studies indicate that returns start to reduce.
Expensive valuations are very often followed by stock market corrections and when the market P/E ratios reach attractive levels, the entire debt portion of investments is shifted back to equities around 16 P/E ratio. This rebalancing exercise from equity to debt and then back to equity is done every time the market reaches the above P/E levels.
The below chart illustrates the returns generated from the 60:40 equity debt dynamic asset allocation strategy compares the returns generated without the asset allocation strategy.
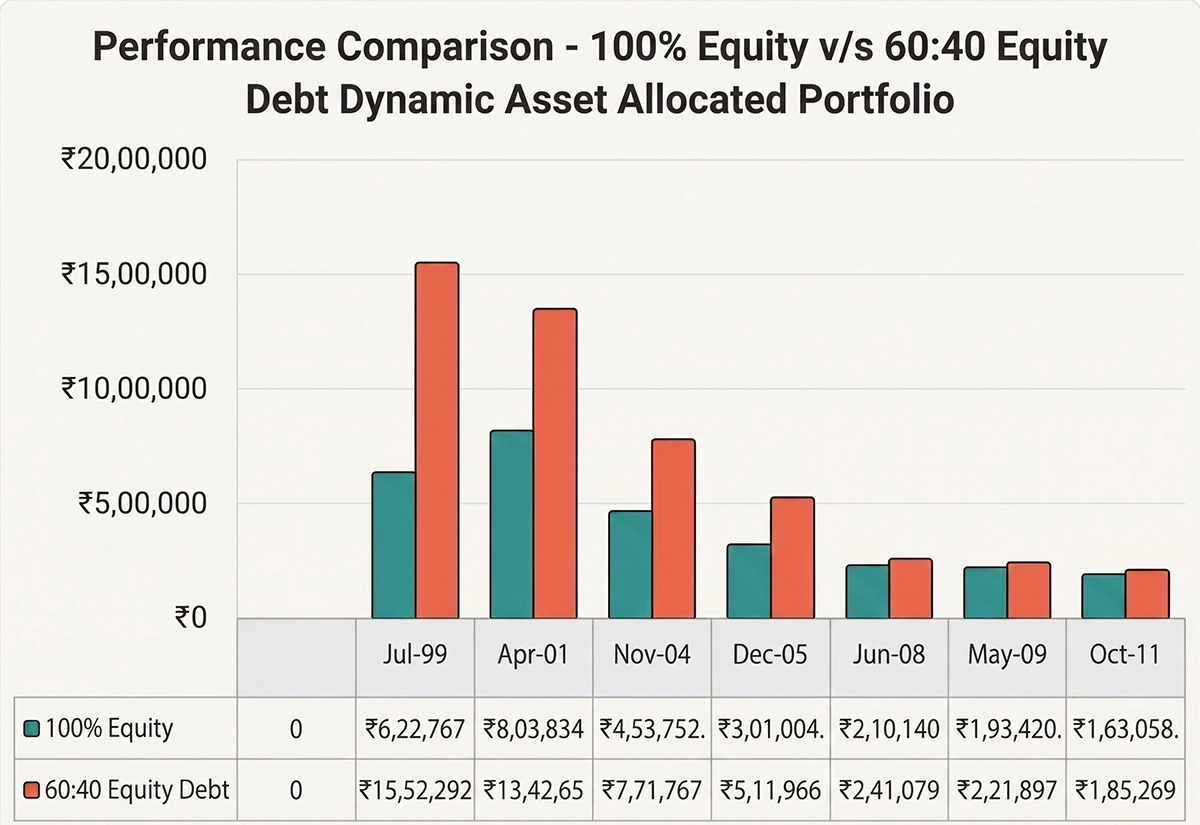
Image description
Title: Performance Comparison - 100% Equity v/s 60:40 Equity Debt Dynamic Asset Allocated Portfolio. Grouped bar chart; the vertical axis runs from ₹0 to ₹20,00,000 in steps of ₹5,00,000. Teal bars show 100% Equity and orange bars show 60:40 Equity Debt. Data table below the chart (100% Equity; 60:40 Equity Debt): first column, no date: 0; 0 | Jul-99: ₹6,22,767; ₹15,52,292 | Apr-01: ₹8,03,834; ₹13,42,65 (last digit not legible in the image) | Nov-04: ₹4,53,752; ₹7,71,767 | Dec-05: ₹3,01,004; ₹5,11,966 | Jun-08: ₹2,10,140; ₹2,41,079 | May-09: ₹1,93,420; ₹2,21,897 | Oct-11: ₹1,63,058; ₹1,85,269. The 60:40 portfolio is higher at every date. The gap is widest at Jul-99 and Apr-01 and narrows at later dates, and both series generally decline from Apr-01 onward.
An investment of ₹ 1,00,000/- in Jul-99 in Dynamic Asset Allocated Portfolio returned ₹ 15,52,292/- as on 19th March 2020, compared to ₹ 6,22,767 generated by investment in a Sensex tracked index fund. The Dynamic Asset Allocated Portfolio outperformed the Sensex tracked index fund by up to 250%.
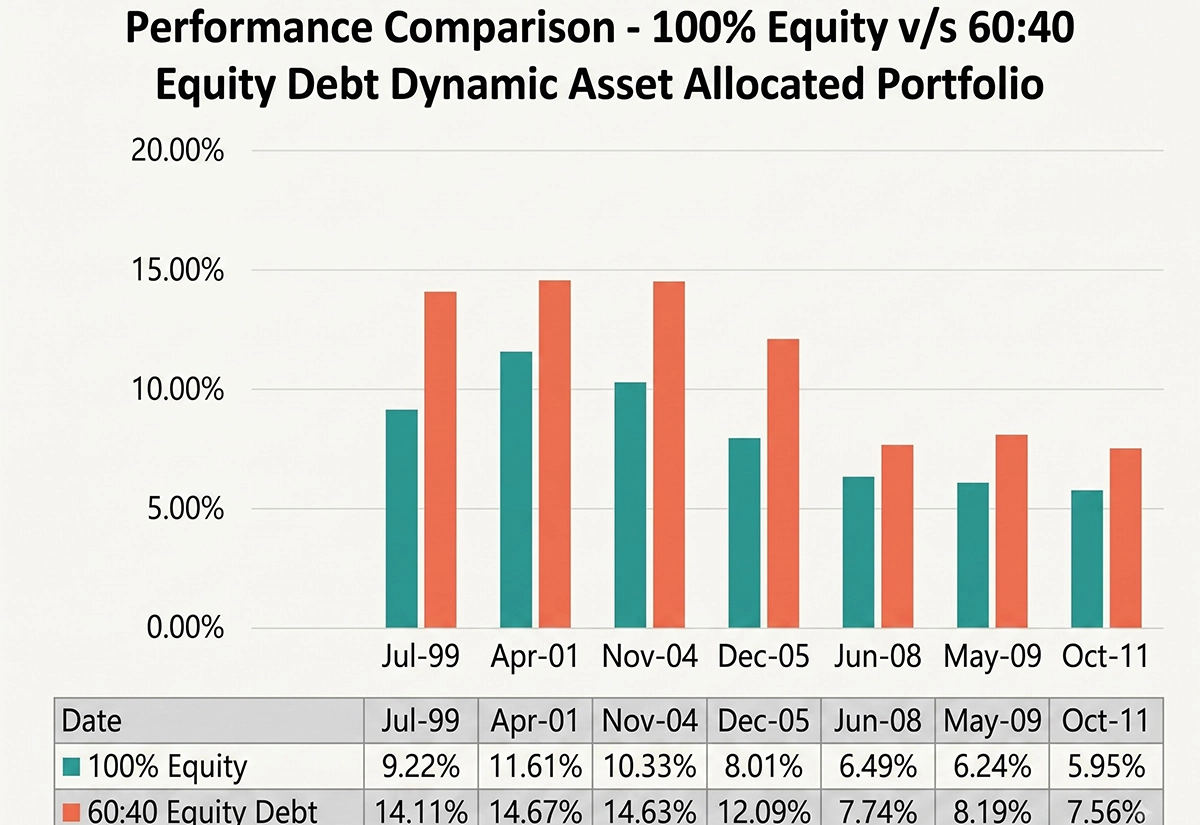
Image description
Title: Performance Comparison - 100% Equity v/s 60:40 Equity Debt Dynamic Asset Allocated Portfolio. Grouped bar chart with a vertical axis from 0.00% to 20.00%, and a data table below it. Date: Jul-99 | Apr-01 | Nov-04 | Dec-05 | Jun-08 | May-09 | Oct-11. 100% Equity (teal bars): 9.22% | 11.61% | 10.33% | 8.01% | 6.49% | 6.24% | 5.95%. 60:40 Equity Debt (orange bars): 14.11% | 14.67% | 14.63% | 12.09% | 7.74% | 8.19% | 7.56%. At every date the 60:40 portfolio shows a higher figure than 100% equity. The gap is widest from Jul-99 to Dec-05 (about 3 to 5 percentage points) and narrows from Jun-08 onward, and both series are lower in the later dates than in the earlier ones.
The CAGR (Compounded Annual Growth Rate) of the Dynamic Asset Allocated Portfolio is up to 5% more than invest and forget equity investment in the Index fund. It can be observed that the return differential increases as the number of years increase; from a difference of 1.61% to 4.91% per year.
While the above strategy sounds very simple to implement, what spoils the party for most investors is their behaviour. It is hard for investors to come out of equity when there seems to be a party at the stock markets every day. It is even harder to stay on the side lines and watch the market gain 20 % – 40% from the date you have changed your asset allocation.
Our recent past is a good reminder of how the markets work. The stock markets reached expensive valuations around the end of 2017 and remained at those levels until the early months of 2020. We have now seen, as in the past, markets correcting and reaching attractive levels. And those who have followed this strategy irrespective of the market temptations stand to gain the most.
The role of a financial adviser in designing your portfolio and subsequent re-balancing can’t be emphasized more. If you have one great, connect with him/her at see how you can implement this, if you don’t, it is time you approach a Fee-Only Financial Planner to help you chart out a strategy that connects with your circumstances, aspirations and goals.
 Book Your Free Introductory Call