How do Financial Planners & Advisors Get Paid in India?

Understanding Financial Advisor Fees & Compensation in India
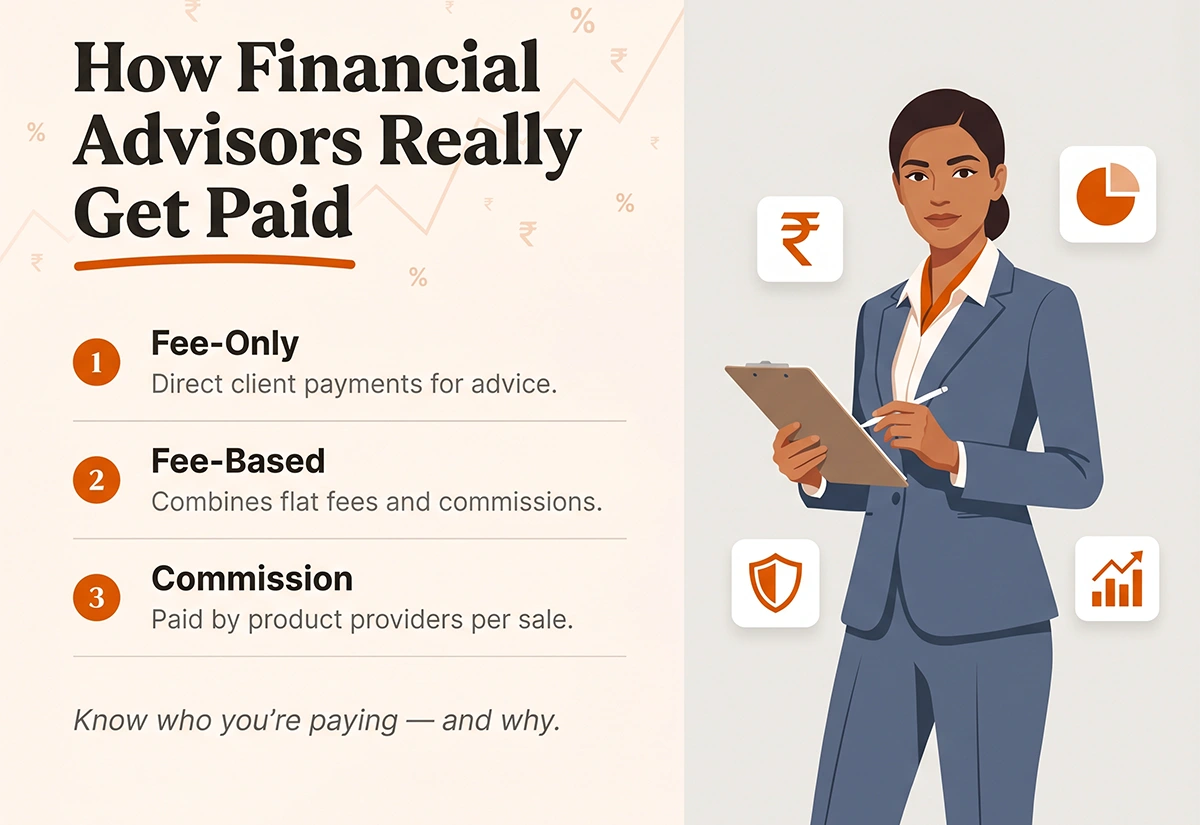
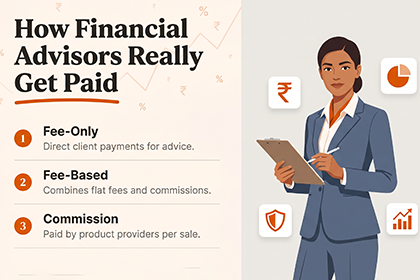
How financial advisors get paid: fee-only, fee-based, or commission paid by product providers.
Image description

Infographic titled 'How Financial Advisors Really Get Paid'. A numbered list explains three payment models: 1. Fee-Only: Direct client payments for advice. 2. Fee-Based: Combines flat fees and commissions. 3. Commission: Paid by product providers per sale. Closing line: 'Know who you're paying — and why.' On the right is an illustration of a woman in a business suit holding a clipboard and pen, surrounded by icons of a rupee sign, a pie chart, a shield and a rising bar chart.

SEBI (Securities Exchange Board of India), with its latest amendments to Registered Investment Adviser (RIA) Regulations, mandates that all registered financial planners can charge only on two bases. A Financial Planner can either charge a fee for financial planning or earn from distribution of financial products. The SEBI regulations prohibit collecting a fee and earning commissions from the same client.


Why Payment Structure Matters?

Understanding how advisors get paid is important because:

  • It shows if advice is biased or neutral
  • It helps you avoid hidden costs
  • It builds trust in financial decisions
  • It helps you choose the right advisor model

Different advisors follow different income models. Let’s look at them one by one.

A financial planner can charge his clients in 3 ways

Flat-Fee Only Financial Planner

A Flat-Fee Only Financial Planner is someone who gets directly compensated by the investor. They charge for the financial plan and advisory services provided to the investor. The fees charged are not linked to the client’s Net Worth or Investments, but are linked to the amount of work required and the expertise or experience of the financial planner. They do not earn any commissions or brokerage from the products or strategies they recommend.

There is no conflict of interest when the planner lists out the action items in a financial plan. They earn no kickbacks or under-the-table payments for anything. These planners are bound by fiduciary responsibility and are mandated by SEBI to keep the best interests of the investors in mind.


Fee-Based Financial Planner

A Fee-Based Financial Planner is someone who charges the investor for planning based on the net worth or the investments held by the client. SEBI allows RIAs to collect a fee up to 2.5% of the client's investments. You will find most planners charging about 1% under this model. The major drawback under this model is that the planner is remunerated only when the client stays invested. A few investors would have experienced their financial planners recommending them not to clear their loans or invest in other non-financial assets.


Distribution of Financial Products

SEBI allows corporate RIAs to earn through distribution or by charging a fee. Corporate RIA Distributors are involved in selling various investment instruments. They could be mutual funds, stocks, insurance products, or any other financial instrument. Their income is generated from the commission or brokerage that is generated by selling those investments. Most people fall for FREE services thinking that they are not paying anything, but fail to realize that the products recommended by them include costs in the form of commissions. There is an element of conflict of interest here, as investors could end up investing in instruments that have high commissions.


Which Payment Model Is Best for You?

There is no single right choice. It depends on what kind of help you need.

Flat-Fee Only

  • Fixed fee for financial advice
  • Best for retirement and education goals
  • No commissions or hidden charges
  • Completely unbiased guidance
  • Ideal for full financial planning

Fee-Based

  • Fee based on investment value (AUM)
  • Suitable for ₹10 lakh+ portfolios
  • Includes regular monitoring and advice
  • May influence investment suggestions
  • Good for ongoing wealth management

Distribution Model

  • Advisor earns commission from products
  • Best for simple investments like SIPs
  • No direct advisory fee charged
  • Not suitable for full financial planning
  • Risk of biased product recommendations

6 Steps a Good Financial Planner Follows

A good financial planner follows the 6-step financial planning process as illustrated below:

  • Establishing and defining the client-planner relationship.
  • Gathering client data and determining goals.
  • Analyzing and evaluating the client's financial status.
  • Developing and presenting financial planning recommendations.
  • Implementing the financial planning recommendations.
  • Monitoring the financial planning recommendations.

Types of Advisers you should stay away from

Investment Recommendations Without Risk Profiling

Understanding the risk profile of an investor and assigning the right asset allocation suitable for their unique needs serves as a strong foundation for the financial plan of an individual. If a planner gives out recommendations without proper risk profiling, it is a sign of grave danger, and it is better to stay away from them.

Promises Guaranteed Returns

Human greed has destroyed more wealth than any other factor and continues to do so. As long as investors fall into the trap of guaranteed returns, you will find con men designing one Ponzi scheme after another. Stay away from people promising guaranteed returns.

Offers Get Rich Quick Schemes

Creating wealth takes time. The human tendency to want to get rich quickly often leads to taking unnecessary risks. Investors fall for traps promising the doubling or tripling of investments and end up losing all their hard-earned money to crooks. It is important to understand the magic of compounding; simple monthly investments of ₹5,000 can create a corpus of more than ₹1,00,00,000 if continued for 30 years at 10% p.a.

Confuses you with Complicated Instruments

Some investors are satisfied only when the adviser presents new products and strategies every now and then. They think that simple products like mutual funds and PPF are not for them. They are often given rosy presentations at fancy hotels without understanding that they are the ones sponsoring such gala dinners through the costs of the complicated instruments they buy.


Choose Wealth Crafts for Transparent Financial Planning

Financial planners and advisors in India follow different payment systems, and each model can influence the advice you receive. The key is not just cost, but clarity and transparency. When you understand how your advisor earns, you can make better financial decisions without confusion and avoid hidden conflicts. Choosing a transparent advisor in India helps you stay confident and build wealth with clear direction. As a registered SEBI financial planner in India , Wealth Crafts clearly explains the fee structure without hiding any terms or conditions.
Recent Blogs

Best NRI Bank Accounts in India: Complete Guide

Compare NRE, NRO, FCNR, GIFT City and offshore accounts to understand their tax benefits, repatriation rules and suitability for NRIs.

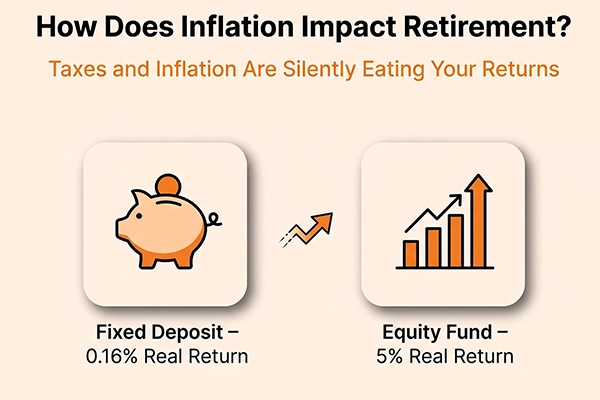
How Does Inflation Impact Retirement Planning?

Learn how inflation impacts retirement savings, income and purchasing power, with strategies to build an inflation-adjusted retirement plan in India.

3 Ways to Invest Using a Minor Account

Learn how to invest using a minor account for your child's future, including PPF, SSY and mutual funds, with key benefits and account requirements.

How Inflation Erodes Wealth and What You Can Do About It

Learn how inflation erodes wealth, reduces purchasing power, impacts savings and investments, and how to protect your finances from rising costs.

A Single Parent's Financial Journey From Tragedy to Triumph

Learn how single parents can manage finances, build an emergency fund, improve insurance coverage, and plan for their child's future.

Long-Term Impact of Personal Loans on Wealth Creation

Learn how personal loans and credit card debt affect savings, investments, and long-term wealth creation, with practical ways to manage debt.

ETFs vs Mutual Funds: Which Is Better?

Compare ETFs vs mutual funds based on costs, trading, flexibility, pricing, and suitability to choose the right investment option for your goals.

Estate Planning in India: A Complete Guide

Learn about estate planning in India, including wills, trusts, powers of attorney, healthcare directives, and beneficiary nominations.
9 Steps to Save for Your House Down Payment

Discover 9 practical steps to save for your house down payment, choose suitable investments, manage risk, and build your home-buying fund.

Child Education Planning: Costs and Investment Strategies

Understand child education costs, inflation, investment options, SIP planning, and strategies to build a corpus for your child's higher education.

7 Steps to Choose the Right Investment Products for Your Financial Goals

Confused about how to choose investment products? Follow these 7 expert-backed steps to align your investments with your financial goals and risk profile.

Investing During a Market Crash: What the Data Really Shows

Should you invest during a stock market crash? See historical Sensex data on returns post-crash and learn why panic-selling hurts investors most.

Dynamic Asset Allocation: What It Is & Why It Works

What is dynamic asset allocation and how does it work? See how a P/E-based equity-debt strategy outperformed the Sensex by up to 250% since 1999.

Understanding Wills: Elements, Types & Why They Matter

What makes a will legally valid in India? Learn its essential elements, types, importance, and what happens to your estate if you die without one.

Should You Prioritize Insurance Before Investing?

Confused about whether to buy insurance or start investing first? Learn why risk management through life, health, and disability cover should come before investments.

Are Index Funds the Right Choice for You?

Wondering if index funds are right for you? Learn why chasing top-performing mutual funds fails and how index funds simplify long-term investing.

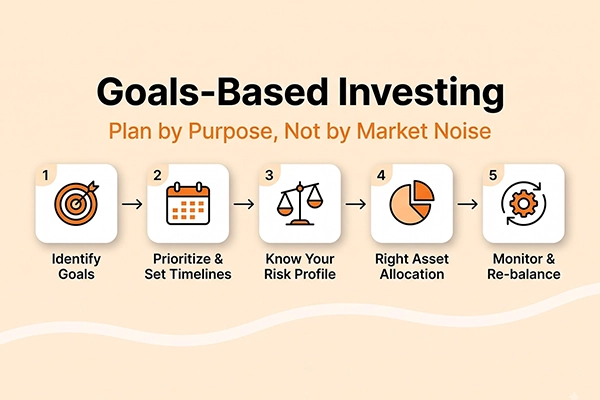
Goals Based Investing vs Market Volatility: A Complete Guide

How does a goals based investment approach help during market volatility? Learn why linking investments to your goals beats reacting to market swings.

The Right Way to Calculate Your Life Insurance

How much life insurance do you really need? Learn the Income Replacement and Need Based methods to calculate the right cover for your family.

REITs Explained: Types, Taxation & How to Invest

What are REITs and how do you invest in them in India? Learn types, tax rules, pros and cons before adding real estate exposure to your portfolio.

Right Time to Buy Your Dream House: A Complete Guide

When is the right time to buy your dream house in India? Explore 4 key factors — economic conditions, interest rates, market trends, and finances.

The Right Time to Invest During a Market Correction

We are all shaken, shaken by the ferocity of the fall in the stock markets. Never have we seen a correction of this magnitude in such a short period.

Why Stock Markets Will Remain Volatile?

The reason why stock markets fluctuate revolves around the theory of demand and supply. If more people want to buy a stock, its market price will increase.

What Is a Super Top-Up Health Insurance Policy and How Does It Work?

Base Policy and Super Top Up Policy are two commonly used options while taking Health Insurance. Health insurance is an important tool to safeguard your financial well-being against unexpected medical expenses. As medical treatments become more expensive

Limited Pay vs Regular Pay — Which Life Insurance Premium Option Is Right for You?

Limited pay vs regular pay – it is easy to get confused between options for your life insurance premium payment. While Life insurance plays a crucial role in securing the financial future of your loved ones.

What Should You Do With Your Life Insurance Policy?

In Indian families, pressure to buy traditional life insurance policies can be strong and multifaceted. Parents often play the “security card,” emphasizing the importance of safeguarding their child’s future and highlighting potential future burdens or painting a picture of an uncertain future without the policy.

Comprehensive Guide on Home Loan Overdraft Facility

Imagine a financial tool that combines the stability of a home loan with the flexibility of an overdraft account – that’s precisely what the Home Loan Overdraft Facility entails.

How to Choose from Different Gold Investment Options

Confused about gold investment options in India? From physical gold to SGBs, this guide compares costs, tax rules, and returns to help you make the right choice.

Index Funds - Advantages, Risks & Suitability

Index Funds are an investment instruments that are based on stock market indices like Sensex or Nifty. These funds are built using a pre-set basket of stocks from different sectors of the economy with predefined weights.

Direct Funds vs Regular Funds - Are Direct Mutual Funds better ?

Confused between direct and regular mutual funds? Compare expense ratios, NAV, and returns to find out which plan helps you grow your wealth long-term.

SSY Interest Rates, Tax Benefits, & Withdrawal Rules

Sukanya Samriddhi Yojana (SSY) is an initiative launched by the Government of India as part of its Beti Bachao, Beti Padhao campaign, (Save the Girl Child, Educate the Girl Child).

7 Types of Financial Ratios to Assess your personal finance & ways to improve them

Understanding the 7 types of financial ratios is a vital exercise that individuals should undertake to assess the state of their financial well-being.

What Should you do with your 401K Account if you Move Back to India

Moving back to your home country after years of working in the US is an exciting chapter. However, it also comes with its own set of financial considerations, especially when it comes to your US retirement savings.

What Are ULIP Charges and How Do They Work

Know about ULIP charges in India covering mortality, policy admin, switching, surrender, and guarantee fees to help you decide if ULIP is worth investing in.

Key Features of NPS (National Pension Scheme)

The National Pension Scheme is a government-sponsored retirement savings plan introduced in India in 2004. It provides a structured approach for individuals to build a retirement fund by making regular contributions.
ESOPs vs RSUs vs ESPPs - Understand the 7 key differences

In today's competitive Indian job market, companies are increasingly turning to equity compensation plans to attract and retain top talent.

12 Risks of Investing ESOPs/RSUs/ESPPs

Imagine your future self, financially secure thanks to a hefty chunk of your employer's stock, a reward for your dedication and hard work.

What Should You Do With Your Life Insurance Policy Decision

Confused about what should you do with your life insurance policy? In Indian families, pressure to buy traditional life insurance policies can be strong and multifaceted.

5 Proven Ways to Build Stable Post Retirement Income in India

Retirement brings major changes in income and life. Investments and savings can help you meet your needs, but a steady income is still essential for daily expenses and regular cash flow.

12 Must Follow Financial Practices Before Moving Abroad

When one is leaving the familiar shores of India for a new life abroad, it may be both exciting and daunting. It's exciting to pack up your bags and head out on a new adventure, but one of the biggest challenges you will face is getting used to a new financial environment.

5 Reasons to Prefer a Fee-Only Financial Planner in India

The term "financial planner" is used often and very loosely. In India, many people call themselves financial planners, the insurance agent, the mutual fund distributor,

How do Financial Planners & Advisors Get Paid in India?

SEBI (Securities Exchange Board of India), with its latest amendments to Registered Investment Adviser (RIA) Regulations, mandates that all registered financial planners can charge only on two bases. A Financial Planner can either charge a fee for financial planning or earn from distribution of financial products.
How to Choose The Best Financial Advisor In India

If you are confused about how to choose the best financial advisor in India, you can thank the Securities Exchange Board of India (SEBI).

6 Reasons to Review Your Financial Plan for Better Financial Health

Reviewing your financial plan matters as much as using a trusted navigation system. When you move forward without regular reviews, you risk heading in the wrong direction.

SEBI's mandatory disclosure requirement

SEBI Disclosures